Most people think about insurance in terms of protecting their home, car, belongings, or business. But what happens when a serious liability claim exceeds the limits of your existing insurance policy?
That’s where Umbrella Insurance can come in.
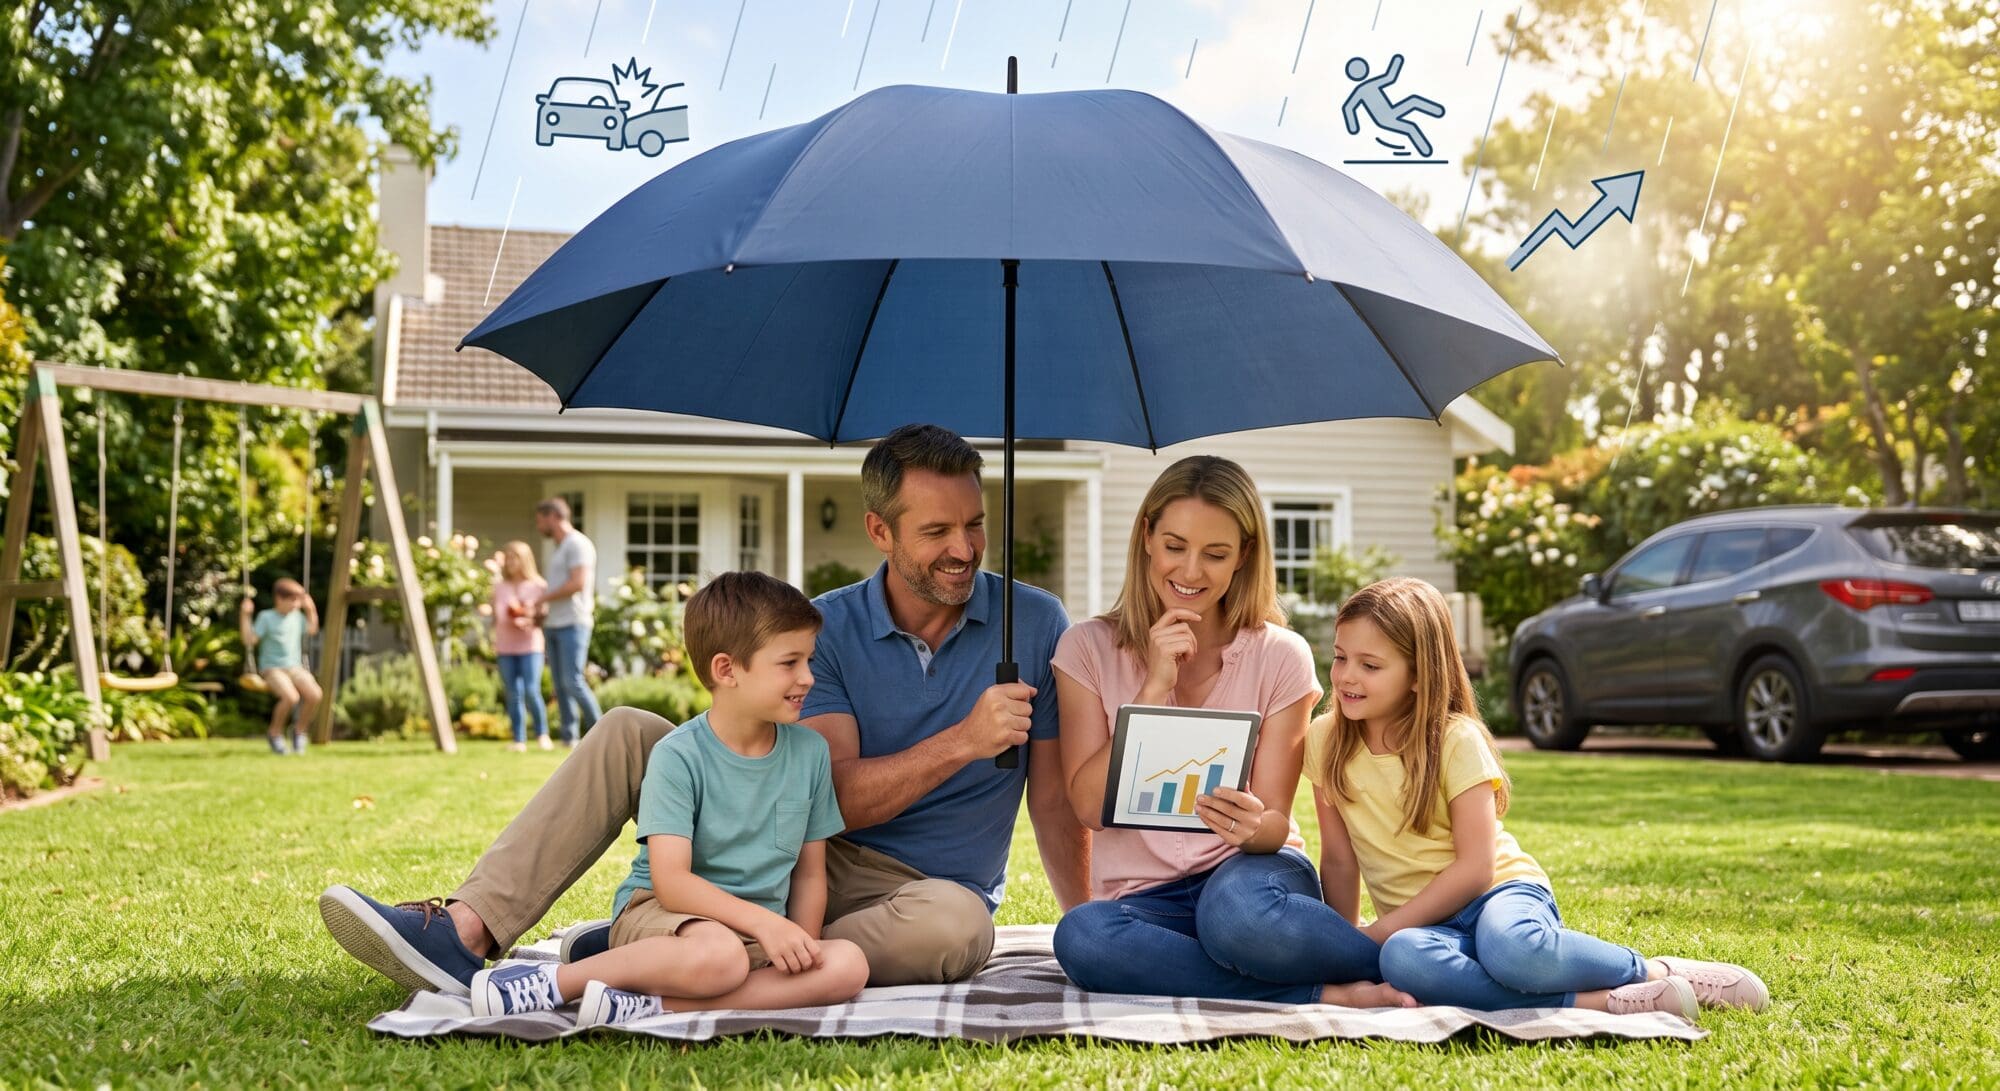
An umbrella policy provides additional liability protection above the limits of certain underlying insurance policies. For homeowners, drivers, landlords, and business owners with significant assets or liability exposure, this extra layer of protection can be worth considering.
But is umbrella insurance actually worth the additional cost?
The answer depends on your assets, lifestyle, existing insurance coverage, and the level of financial risk you’re comfortable taking on.
What Is Umbrella Insurance?
Umbrella Insurance is a type of excess liability coverage designed to provide additional protection after the limits of certain underlying liability policies have been exhausted.
For example, imagine you are involved in a serious auto accident and are found legally responsible for damages that exceed the liability limit on your auto policy.
Without additional coverage, you could potentially be responsible for the amount above your policy limit.
An umbrella policy may provide additional liability protection, subject to its terms, conditions, exclusions, and required underlying insurance.
Umbrella insurance isn’t designed to replace your existing policies. Instead, it generally sits above them and provides an additional layer of protection.
Why Might Someone Need Umbrella Insurance?
A major liability claim can happen to almost anyone.
For example:
-
A serious car accident causes significant injuries.
-
A guest is severely injured at your home.
-
A child accidentally causes substantial damage to someone else’s property.
-
You own a rental property and face a significant liability claim.
-
You have a pool or other feature that increases your liability exposure.
-
You regularly host guests or events at your property.
Your standard homeowners insurance or auto insurance provides liability protection, but those policies have limits.
Umbrella insurance can provide additional protection when a serious covered claim goes beyond those limits.
How Much Does Umbrella Insurance Cover?
Umbrella policies are commonly available with liability limits starting around $1 million, with higher limits available depending on the insurer and the insured’s circumstances.
The appropriate amount isn’t the same for everyone.
When determining how much umbrella coverage you may need, consider:
-
Your assets
-
Your income
-
Your home
-
Investments
-
Savings
-
Vehicles
-
Rental properties
-
Potential future income
-
Your overall liability exposure
Your insurance professional can help you evaluate your circumstances and determine whether additional liability protection makes sense.
Umbrella Insurance Can Protect More Than Your Home
One advantage of umbrella insurance is that it isn’t necessarily limited to your house.
Depending on the policy, umbrella coverage can provide additional liability protection over underlying policies such as:
-
Landlord Insurance
-
Certain recreational vehicle policies
The exact policies covered by an umbrella can vary, so it’s important to review the requirements and terms of the policy you’re considering.
Who Should Consider Umbrella Insurance?
Umbrella insurance isn’t only for extremely wealthy individuals.
It may be worth considering if you:
-
Own a home
-
Have significant savings or investments
-
Own multiple vehicles
-
Have teenage drivers
-
Own rental property
-
Have a pool or trampoline
-
Frequently host guests
-
Travel frequently
-
Have substantial future income to protect
-
Own assets that could make you a larger target for liability claims
You don’t necessarily need millions of dollars in assets before umbrella insurance becomes worth discussing.
The potential financial consequences of a serious liability claim are another important consideration.
What About Teenage Drivers?
Teen drivers can be one reason families consider additional liability protection.
New drivers have less experience behind the wheel, and accidents involving serious injuries can result in substantial claims.
If you have a teenage driver in your household, reviewing your auto insurance liability limits and discussing umbrella insurance with your agent may be worthwhile.
An umbrella policy doesn’t prevent accidents from happening, but it may provide additional financial protection if a covered liability claim exceeds your underlying auto insurance limits.
Rental Property Owners May Want Extra Protection
If you own rental property, you may have additional liability exposure beyond your personal residence.
A tenant or visitor could potentially be injured on the property, resulting in a liability claim.
Landlord insurance can provide important protection, but property owners with multiple rentals or significant assets may also want to consider additional liability protection through an umbrella policy.
Discuss your rental properties with your insurance professional so they can determine how the properties can be incorporated into your overall insurance program.
Umbrella Insurance Isn’t Just for Homeowners
Even renters can potentially benefit from umbrella insurance.
You don’t have to own a home to have assets or income that could be exposed to a major liability claim.
Someone who rents an apartment, owns vehicles, has savings, or has substantial future income may still want to discuss personal umbrella insurance with an insurance professional.
Your underlying renters or auto policy would typically need to meet the umbrella insurer’s requirements.
What Doesn’t Umbrella Insurance Cover?
Umbrella insurance provides broad liability protection, but it isn’t a policy that covers everything.
It generally doesn’t replace:
-
Health insurance
-
Homeowners insurance
-
Auto insurance
-
Property insurance
-
Life insurance
-
Business insurance
Umbrella policies also have their own exclusions and conditions.
For example, certain intentional acts, business activities, and other risks may be excluded or subject to specific requirements.
That’s why it’s important to read and understand the actual policy rather than assuming umbrella insurance covers every possible loss.
You May Need Higher Underlying Limits
Before purchasing an umbrella policy, an insurer may require you to maintain certain minimum liability limits on your underlying policies.
For example, your umbrella insurer may require specific liability limits on your auto and homeowners insurance before providing umbrella coverage.
This means you may need to increase your existing liability limits before an umbrella policy can be added.
While that could increase your underlying insurance premium, it can also provide a stronger overall liability protection strategy.
Is Umbrella Insurance Expensive?
Compared with the amount of additional liability protection it can provide, umbrella insurance can be relatively affordable for many qualifying individuals.
However, the cost varies based on factors such as:
-
Amount of coverage
-
Number of vehicles
-
Drivers in the household
-
Driving history
-
Properties owned
-
Rental properties
-
Location
-
Claims history
-
Underlying insurance limits
Because every situation is different, getting a quote is the best way to determine what umbrella coverage could cost for you.
Continue Learning About Your Insurance Options
Umbrella insurance is only one part of protecting your financial future. Your home, auto, renters, and other policies all play an important role in your overall insurance strategy.
Umbrella Insurance vs. Higher Liability Limits
You may be wondering whether it’s better to simply increase the liability limits on your existing policies instead of purchasing an umbrella policy.
Increasing your underlying liability limits can certainly provide additional protection.
However, an umbrella policy may provide a much higher level of additional liability coverage for a comparatively lower cost than continually increasing the limits of every underlying policy.
The right approach depends on your circumstances, existing coverage, and the options available through your insurance carrier.
Review Your Insurance Before Buying an Umbrella Policy
If you’re considering umbrella insurance, start by reviewing your existing policies.
Look at your:
-
Auto liability limits
-
Homeowners liability limits
-
Renters liability limits
-
Landlord coverage
-
Existing umbrella coverage
-
Deductibles
-
Exclusions
Your insurance professional can then determine whether your current policies meet the requirements for an umbrella policy and whether your overall liability protection is appropriate.
Work With an Independent Insurance Agency
Determining whether Umbrella Insurance is worth it can be difficult when you’re trying to evaluate your entire insurance portfolio at once.
An independent insurance agency can review your existing policies and compare available umbrella coverage options from multiple insurance carriers.
Rather than simply purchasing the largest policy available, you can discuss your assets, lifestyle, vehicles, properties, and other potential liability exposures to determine what level of coverage makes sense.
Final Thoughts
So, is umbrella insurance worth it?
For some people, absolutely.
If you have significant assets, multiple vehicles, rental properties, teenage drivers, substantial income, or other liability exposures, an umbrella policy can provide an additional layer of financial protection against serious covered claims.
You don’t need to be wealthy to consider umbrella insurance. What matters is understanding how much financial risk you could potentially face if a liability claim exceeded the limits of your existing insurance.
Reviewing your current home, auto, renters, and other liability coverage can help you determine whether an umbrella policy is worth considering.
If you’re ready to explore your options, get an insurance quote and speak with an insurance professional about whether umbrella coverage makes sense for your situation.